Enlarged Europe Shipments Rise 10% on BEV Growth; North America Down 12% Following Planned Production Shutdowns
Stellantis N.V. today released its estimated consolidated shipments for Q3 2026. The term “shipments” describes the volume of vehicles delivered to dealers, distributors, or directly from the Company to retail and fleet customers, which generally drive revenue recognition.
Consolidated shipments for the three months ended September 30, 2026, were an estimated 1.3 million units, down 1% year-over-year. BEV growth in Enlarged Europe was offset by lower volumes in North America, reflecting the planned summer production shutdown, and in Middle East & Africa, mainly due to a drop in the Turkish market.
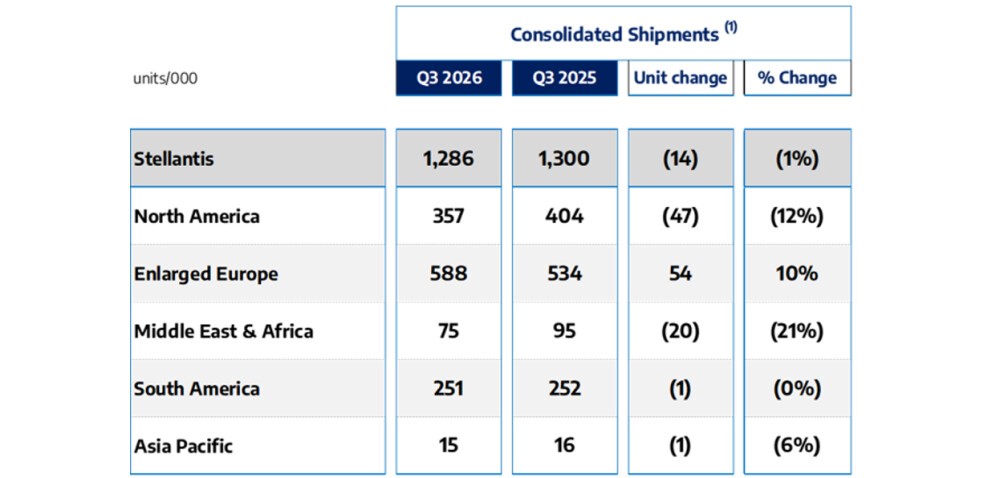
• In North America, Q3 shipments declined by approximately 47 thousand units, or 12% year-over-year, primarily due to
planned production downtime largely affecting certain Jeep® models, including the Grand Cherokee and Compass, each decreasing by approximately 25 thousand units year-over-year. The decrease in shipments was partially offset by stronger Ram performance, with shipments increasing by approximately 17 thousand units year-over-year, driven by demand for new and refreshed products and expanded powertrain offerings, including the Ram 1500 light-duty HEMI® V8 and the new Ram 1500 TRX.
• In Enlarged Europe, Q3 shipments increased by approximately 54 thousand units, or 10% year-over-year. Growth came from both Stellantis and Leapmotor-branded vehicles, driven by BEV shipments. For Stellantis brands, shipment growth was driven primarily by approximately 26 thousand units of the Smart Car platform nameplates, including the Citroën C3 and C3 Aircross, Opel/Vauxhall Frontera, and Fiat Grande Panda. The new Fiat 500 Hybrid and the new Jeep Compass also contributed positively, adding approximately 6 thousand units and 5 thousand units, respectively. To a lesser extent, Light Commercial Vehicle shipments also supported growth, increasing by approximately 7 thousand units, led by BEV versions. These gains were partially offset by a decline of approximately 28 thousand units in shipments of other models, including Opel Corsa, Opel Mokka, Citroën C4, Alfa Romeo Junior and Peugeot 2008. Leapmotor-branded vehicle shipments increased by approximately 34 thousand units to 44 thousand units, supported by the new launches of the B10 and the B03X.
• In Middle East & Africa, shipments declined by approximately 20 thousand units, or 21% year-over-year, primarily reflecting lower volumes in Türkiye, down approximately 21 thousand units amid weaker market conditions and reduced shipments of imported vehicles due to the planned launch in October 2026 of local production of small vans. Higher shipments in Algeria and Morocco more than offset lower volumes in the Gulf Cooperation Council countries, which were impacted by the regional conflict.
• In South America, shipments decreased slightly year-over-year, by approximately 1 thousand units. The growth in Brazil, up approximately 13 thousand units, due to favorable industry conditions, was more than offset by lower shipments in other markets, mainly in Argentina, where shipments declined by approximately 11 thousand units impacted by weaker market conditions.
• In Asia Pacific, Q3 shipments at 15 thousand units declined by approximately 6% year-over-year, primarily due to lower shipments in Japan, amid weaker market conditions and an unfavorable comparison with higher prior-year volumes from product launches. Higher volumes in India, including from Smart Car platform vehicles, partially offset the decline.